
Equity Release lending up 11% in 2025 – ERC
Total lending increased from £2.3bn in 2024 to £2.57bn last year.

Equity release lending grew by 11% in 2025, according to the latest research from the Equity Release Council (ERC).
Total lending increased from £2.3bn in 2024 to £2.57bn last year.
Research found that 40% of borrowers used equity release for home improvements (21%), holidays (6%), cars (4%), or gifting to family (13%).
More than a quarter of advisers (26%) said customers were using equity release to clear mortgage balances.
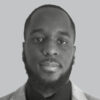
Jim Boyd (pictured), CEO of the Equity Release Council, said: “Growth of 11% underlines the increasingly important role housing wealth is playing in supporting financial resilience and choice in later life.
“It reflects something far bigger than short-term market movements – equity release is proving vital to meeting people’s social and economic needs.
“Modern products are more flexible and secure than ever and, for many homeowners, accessing housing wealth is now a core part of their retirement planning, helping them enjoy financial freedom and a better quality of life.”
Boyd added: “Releasing property wealth now supports around £1 in every £90 spent by retired households.”
Total lending for Q4 2025 was £632m, up 1.6% from Q4 2024 (£622m).
The average release rose to £123,174, an increase of 5.7% year-on-year.
There were 1,468 further advances in Q4 2025, compared to 1,411 in Q4 2024.
Four in five advisers (80%) forecast more lending in 2026, with only 2% expecting a fall.
Nearly the same number expect overall customer growth next year.
David Burrowes, chair of the Equity Release Council, said: “Increasingly, releasing equity is part of homeowners’ retirement plans.
“Almost four in every ten future retirees (38%) are on track for a retirement income below the Pensions UK ‘minimum standard’.
“Demographic and economic pressures mean the demand is there and likely to grow. Innovations in product design are making modern equity release more flexible and more secure, making it more attractive to consumers.”
The Equity Release Council cited long-term growth supported by increased collaboration in later life lending and regulatory engagement.
In Q1 2026, the Financial Conduct Authority (FCA) is launching a market study into later life lending and property-based solutions for those borrowing into retirement.
Burrowes added: “This is an important step which reflects the reality that borrowing in later life is becoming more common and that the market must continue to evolve to deliver good consumer outcomes.
“That regulatory focus, combined with collaboration and continued product innovation, gives us confidence in the sector’s long-term direction.
“We have never had a better opportunity to bridge the retirement later life funding gap.”
REACTION:
Lorna Shah, managing director, retail retirement at L&G:
“These figures suggest that equity release has become an increasingly mainstream consideration as people seek to draw on the funds tied up in their homes to achieve their retirement goals and individual lifestyles.
“L&G works closely with financial advisers and the broader industry to ensure customers are able to make informed decisions that best meet their retirement income needs.
“This ongoing and collaborative dialogue helps ensure that the later life lending sector remains innovative, responsive and customer-driven.”
Mark Gregory, founder and CEO of Equity Release Group:
“The Equity Release Council’s latest figures reflect what we’ve also been seeing on the ground for a while now and that is that demand in this market isn’t fading but evolving.
“In 2025, Equity Release Supermarket delivered a 16% uplift in completed cases year on year, showcasing that demand is being driven by structural change rather than short-term market conditions, hence there is a real underlying need for equity release.
“More people today are reaching later life still carrying mortgage debt, often on fixed or reduced incomes, and trying to make their money last longer.
“When you combine that with longer life expectancy and the slow demise of defined benefit pensions, it’s no surprise that homeowners are starting to look at their property wealth alongside pensions and savings, not instead of them.
“However, growth alone is not the only story here. What’s evolved the most is how people want to access advice. Growth hasn’t come from pushing a single product or relying on one route to market.
“It comes from giving people more choice in how they engage, the personalisation, the choice and supporting that with best-in-class advice and clear consumer duty safeguards.
“That’s what we’ve seen reflected in our channel mix – consumers are now accessing and researching products in a variety of ways. smartER™ now accounts for almost a fifth of our business, and by expanding partnerships with organisations such as StepChange, we’ve been able to reach a broader audience, including customers who may not previously have realised this was an option.
“We know digital engagement works but only when it’s paired with quality advice, clear suitability, and the kind of robust assessments that protect customers and support good outcomes.
“As demand broadens in 2026, at Equity Release Supermarket, we expect more customers to arrive better informed and more comparison-led, which will reward firms that communicate clearly, set expectations early, and keep the process straightforward from first enquiry to completion.”
Sadna Zaman, home finance proposition manager at Canada Life:
“Robust growth of the equity release market last year highlights the increasing recognition of property wealth as an essential component in retirement planning.
“As life expectancy rises and pension savings are stretched further, later life lending is playing a valuable role in helping homeowners maintain their income and achieve greater financial flexibility in retirement.
“Last year we saw a marked shift in the conversation around the role of property wealth as a critical part of the toolkit for retirement planning, driven by the FCA’s review of the mortgage market.
“It has been hugely positive to see the regulator focus on the potential of the later life lending sector to meet the evolving needs of customers.
“With a forward-looking market study and a review of advice rules scheduled for early this year, the regulator has set the stage for a busy year of policy development and engagement.
“This will help drive further growth in the sector, offering advisers and their clients greater choice and support in later life lending.”
Dave Harris, CEO of more2life:
“An 11% annual rise in equity release lending is welcome and shows that demand for, and understanding of, lifetime mortgages is growing among both consumers and advisers. It is also encouraging that four in five advisers expect further lending growth in 2026.
“However, these figures also hide a bigger issue. Despite the rise in lending value, the number of new customers grew by less than 1% year-on-year.
“Lifetime mortgages still account therefore for less than 10% of a later life lending market worth around £25bn a year. Given the range of products now available, that gap feels hard to justify.
“We believe too many over-55 homeowners, who could benefit from modern lifetime mortgages, are still not seeing them as part of their advice journey.
“Products have changed. Many now allow interest to be fully or partly paid, offer zero early repayment charges, and continue to provide certainty of tenure, fixed rates for life and a no negative equity guarantee.
“These are not fringe options. They sit alongside RIOs and mainstream later life mortgages and should be considered in the same conversation.
“There is also a clear access issue. Many advisers still do not cover later life products themselves and that can limit outcomes if referral routes are not in place.
“Forming strong relationships with trusted specialists should be standard practice, not the exception, if advice is to reflect the real choices available to older borrowers.
“The FCA’s ongoing later life lending study is an important step, particularly around holistic advice. But advisers do not need to wait for regulation to change.
“The profession can act now by making sure every customer is assessed across all suitable options. Demand is clearly there.
“The challenge now is to ensure advice keeps pace, so more customers can access solutions that genuinely support their later life goals.”
Kay Westgarth, head of retirement distribution, Aviva:
“The latest figures from the Equity Release Council underline the growing and increasingly mainstream role that housing wealth is playing in retirement planning.
“An 11% rise in lending in 2025 reflects not just market momentum, but the way modern equity release products are being used more positively, whether that’s improving homes, supporting family, or enhancing quality of life in later years.
“What’s particularly encouraging is the continued growth seen in Q4, alongside rising average loan sizes and strong levels of adviser confidence looking ahead to 2026.
“As products become more flexible and consumer understanding improves, equity release is rightly being viewed as a long term financial planning tool rather than a last resort.”
Sophie Walsh, head of equity release at Royal London:
“Equity Release Council data shows the later life lending market grew around 11% year on year in 2025, even as the number of customers fell, as average borrowing increased.”
“That pattern points to a more planning led market, where clients are making fewer but more significant decisions, reinforcing why later life lending must sit within proper retirement and later life planning, supported by clear, holistic advice rather than transactional recommendations.”
Paul Carter, CEO of Pure Retirement:
“The latest figures from the Equity Release Council demonstrate the extent to which lifetime mortgages continue to fulfil the needs of over-55s.
“The rising average lump sum borrowing on both an annual and quarterly basis demonstrate the confidence new customers have in releasing the equity in their homes, while the increasing levels of people taking out further advances underlines how comfortable those who’ve already taken out equity release are in returning to release additional funds.
“The quarterly increases in customer numbers are also positive, but the fact that 2025 as a whole saw a reduction on an annual basis points towards the work needed to ensure later life lending truly becomes a mainstream solution going forward, especially as Canada Life’s recent research has suggested that financial advisers are failing to mention equity release as an option in 93% of conversations with home owners about retirement.
“With lifetime mortgages clearly meeting a very real societal need among those utilising them, the latest Council figures should spur us on as a sector to ensure they’re part of widespread financial planning in 2026 and beyond.”
Related

Equity Release Council and AMI to host Later Life Lending Summit North
Air and Mortgage Brain partner to support holistic later life lending advice

Brilliant Solutions joins Equity Release Council

Bank lending growth to hit three-year low in 2027, EY says

54% of historical Japanese knotweed locations recorded near built-up areas, analysis finds

Commercial property values down 0.9% in Q3, CBRE finds

Fowey tops house price growth for picturesque UK towns – Alto
BTR investment surpasses £900m as volumes reach record high in Q3 – Savills

Nearly half of homeowners carry out property research in secret – Zoopla

Four in 10 London flats resold at a loss, analysis finds
Preston is UK’s best place to sell a home, research finds
