
Eight in 10 homeowners want advisers to discuss redundancy risk, research reveals
Three in five (58%) respondents said they expect redundancy risk to increase within the next five years.

Homeowners overwhelmingly want their mortgage advisers to raise the risk of redundancy, but few do, according to research from Walsham Brothers.
Walsham Brothers found that eight in 10 (81%) homeowners believed mortgage advisers should routinely discuss how customers would manage their mortgage payments if they become unemployed.
This comes at a time of significant concern about the risk of redundancy.
Three in five (58%) respondents said they expect redundancy risk to increase within the next five years, rising to 61% of Generation X (ages 46 to 61) and 63% of Boomers (ages 62 to 80).
Yet, among those respondents who have used or arranged a mortgage, only 26% recalled their adviser having that conversation.
23% said they couldn’t remember and 20% didn’t use a mortgage adviser.
Meanwhile, the findings also revealed a lack of awareness of all the relevant protection options available.
Almost three in five (56%) said they weren’t aware that insurance covering involuntary redundancy/unemployment could be purchased on its own, without accident or sickness cover.
Only one in 10 (10%) said they have insurance to protect their income and payments if they were made redundant.
Of those who had considered taking out redundancy cover but decided against it, cost represented the main barrier (32%), followed by ‘didn’t think I needed it’ (17%).
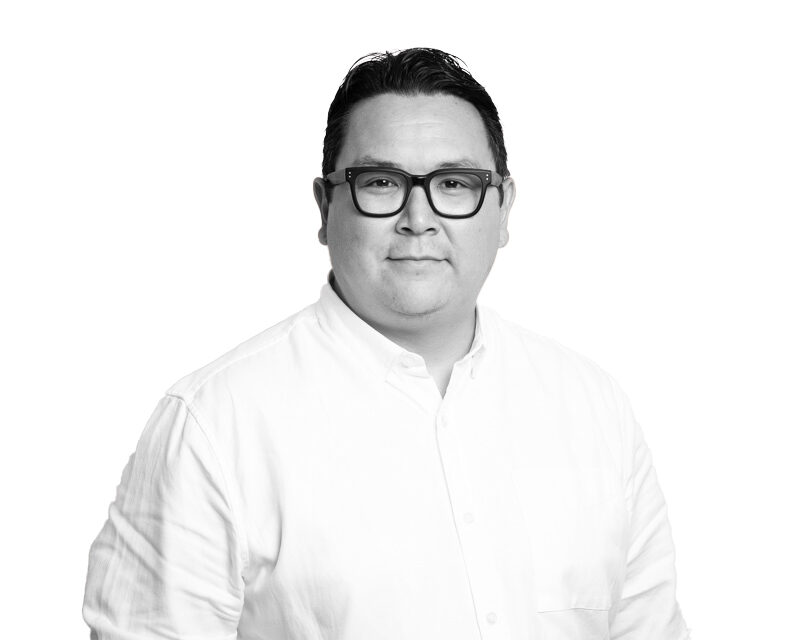
Jamie Leong (pictured), senior manager – product and propositions at Walsham Brothers, said: “Consumers have told us they want advisers to highlight the risk of redundancy to them, at a time when that risk feels very real.
“But few recall this happening; either clear that it didn’t, or not clear either way. Plus, a fifth simply didn’t use a mortgage adviser.
“There are educational and awareness needs on many levels here; from the value of taking advice when making a home purchase – probably the biggest purchase we make it our lifetime – to advisers discussing all risks, grounding them in reality and making it clear that redundancy cover is low-cost.”
He added: “For example, a 38-year-old could expect to pay £23.67 a month for £1,500pm benefit.
“At a time when the FCA’s Pure Protection Market Study is helping shine a light on accessibility, we all need to be looking at consistent and innovative ways to close the protection gap for the three fifths (59%) of people who have never considered their protection needs.
“Some cover is always better than none. And cover for a risk that’s not included as part of traditional income protection – in other words, redundancy – could arguably be considered an essential for all.”
Related

Weight loss treatment disclosures among protection applicants rise to 1.3% – UnderwriteMe

Six in 10 consumers have never received a protection quote, AMI finds

Nine million UK adults financially support older relatives, Canada Life finds

The Wealthy Advisers Club partners with CIExpert
Almost half of Millennials rely on inheritance to meet financial goals – Alliance Witan

A third of aspiring homeowners struggle to understand property jargon, research reveals
Royal London reports average protection underwriting turnaround of 1.5 working days
Valuation errors and rebuild cost awareness driving underinsurance – Prestige Underwriting
Trust in private medical insurance reaches highest point in two years – Fairer Finance

TMG Mortgage Network adds Walsham Brothers to GI panel
Fire accounts for one in 40 home insurance claims – Tesco Insurance
